
Top Homeowners Insurance Agency in Largo, Florida
Finding the right homeowners insurance in Largo, Florida requires more than comparing monthly premiums. Between Florida’s hurricane exposure, aging roofs, changing replacement costs, and the insurance needs of established Pinellas County neighborhoods, homeowners have several important decisions to make when protecting their property.
At Ackerman Insurance, we help Largo homeowners navigate those decisions by comparing available insurance options, explaining policy differences, and identifying coverage appropriate for their homes.
Whether you’re purchasing your first property, reviewing an existing policy, or searching for more competitive rates, our team can help.
If you’re looking for a top homeowners insurance agency serving Largo, FL, Ackerman Insurance offers personalized assistance from our Tampa Bay office.
Discover Largo, Florida: An Established Pinellas County Community
Largo is one of Pinellas County’s major residential communities, situated between Clearwater and St. Petersburg with convenient access to the Gulf beaches, shopping, parks, and the greater Tampa Bay region.
Unlike newer suburban communities that have developed rapidly over the past two decades, Largo features many established neighborhoods, mature trees, traditional Florida homes, and residential areas that have evolved over generations.
The community is particularly well known for Largo Central Park, its extensive recreation facilities, and nearby attractions such as the Florida Botanical Gardens, Heritage Village, and John S. Taylor Park.
Largo Central Park is a major community gathering place, while the surrounding parks and cultural destinations help give Largo its own identity beyond its proximity to the beaches.
Residents also enjoy convenient access to Indian Rocks Beach, Belleair Beach, and other Gulf Coast destinations.
For homeowners insurance purposes, Largo’s residential diversity is significant. A single-family home built in the 1970s may have different underwriting requirements than a renovated property, newer residence, condominium, or higher-value home.
Understanding those differences is an important part of finding suitable homeowners insurance.
Why Largo Homeowners Need the Right Insurance Coverage
Every home has its own characteristics, and those characteristics can affect insurance eligibility, available coverage, and premiums.
For example, insurers may consider a home’s age, roof condition, construction materials, electrical systems, plumbing, replacement cost, previous claims, and wind-resistant features.
Largo homeowners may also face considerations related to severe weather, heavy rainfall, and potential flooding.
Choosing coverage without reviewing these details could leave a homeowner paying more than necessary or carrying inadequate protection.
Ackerman Insurance helps homeowners evaluate the bigger picture before selecting a policy.
What Does Homeowners Insurance Cover in Largo?
Although coverage varies by insurance carrier and policy, homeowners insurance typically includes several essential protections.
Dwelling Coverage
Dwelling coverage helps pay to repair or rebuild the physical structure of your home following qualifying covered losses. An appropriate dwelling limit should reflect estimated rebuilding costs, which may differ considerably from the property’s market value.
Personal Property Protection
Furniture, electronics, clothing, appliances, and other belongings may be covered following qualifying losses. Additional coverage may be appropriate for certain valuable possessions, depending on policy limitations.
Personal Liability Insurance
Personal liability coverage may help protect homeowners financially when they are legally responsible for certain injuries or property damage. Homeowners with pools, substantial assets, or other liability exposures may want to review higher coverage limits.
Other Structures
Detached garages, fences, sheds, and other qualifying structures may be covered under a separate portion of the homeowners policy.
Additional Living Expenses
If covered property damage temporarily makes your home uninhabitable, additional living expense coverage may help pay qualifying increased living costs during repairs.
Homeowners Insurance for Largo’s Older Homes
One of Largo’s most important insurance considerations is its established housing stock. Many residential properties were built decades ago, and insurers may pay close attention to the condition of their major systems.
Important considerations include:
- Roof age and remaining useful life
- Electrical panels and wiring
- Plumbing materials and condition
- Water heater age
- HVAC equipment
- Prior renovations and permitted improvements
- Wind mitigation features
A homeowner who has recently replaced a roof or completed major upgrades should ensure that accurate information is provided when obtaining insurance quotes. These improvements can sometimes affect eligibility, available carriers, and premiums.
For certain older homes, insurers may also request a four-point inspection to evaluate the roof, electrical, plumbing, and HVAC systems.
Hurricane and Windstorm Protection in Largo, FL
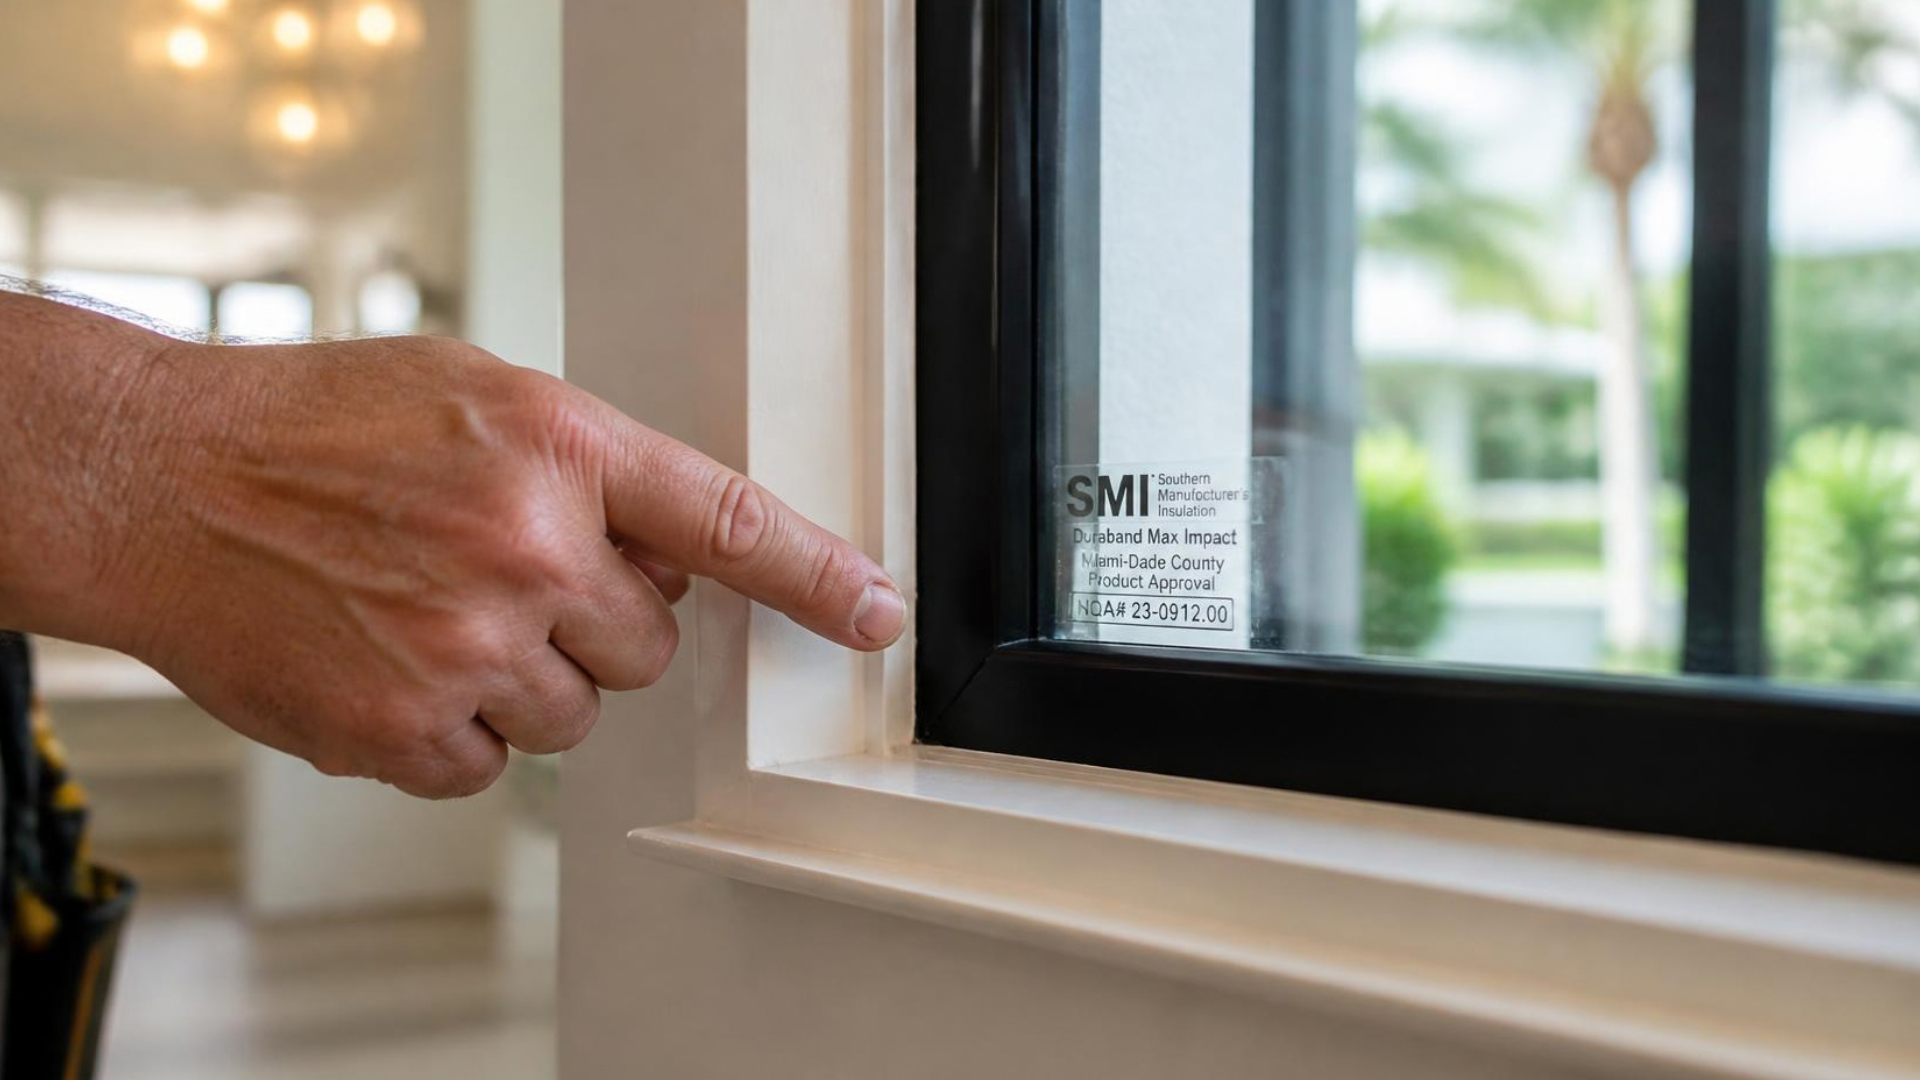
Although Largo is not entirely a beachfront community, its location within Pinellas County makes hurricane and windstorm protection an important consideration.
Tropical systems can bring damaging winds, falling trees, flying debris, roof damage, and heavy rainfall throughout the Tampa Bay region.
Homeowners should understand whether their policy covers qualifying wind damage, which exclusions apply, and how their hurricane deductible works.
Some Florida homeowners policies include percentage-based hurricane deductibles. For example, a 2% deductible on a dwelling insured for $400,000 would equal $8,000, assuming the percentage applies to that insured amount. Understanding this potential expense before a storm is essential.
Wind Mitigation and Potential Insurance Savings
Largo homeowners may be able to improve their insurance options by documenting qualifying wind-resistant construction features.
A wind mitigation inspection can identify characteristics such as roof-to-wall connections, roof deck attachment, secondary water resistance, and hurricane opening protection.
Qualifying improvements may include impact-resistant windows, hurricane shutters, or certain roof upgrades. Available credits depend on the insurance carrier and the specific features of the home.
For homeowners with older properties that have undergone renovations, updated wind mitigation documentation may be particularly worthwhile.
Flood Insurance Considerations in Largo
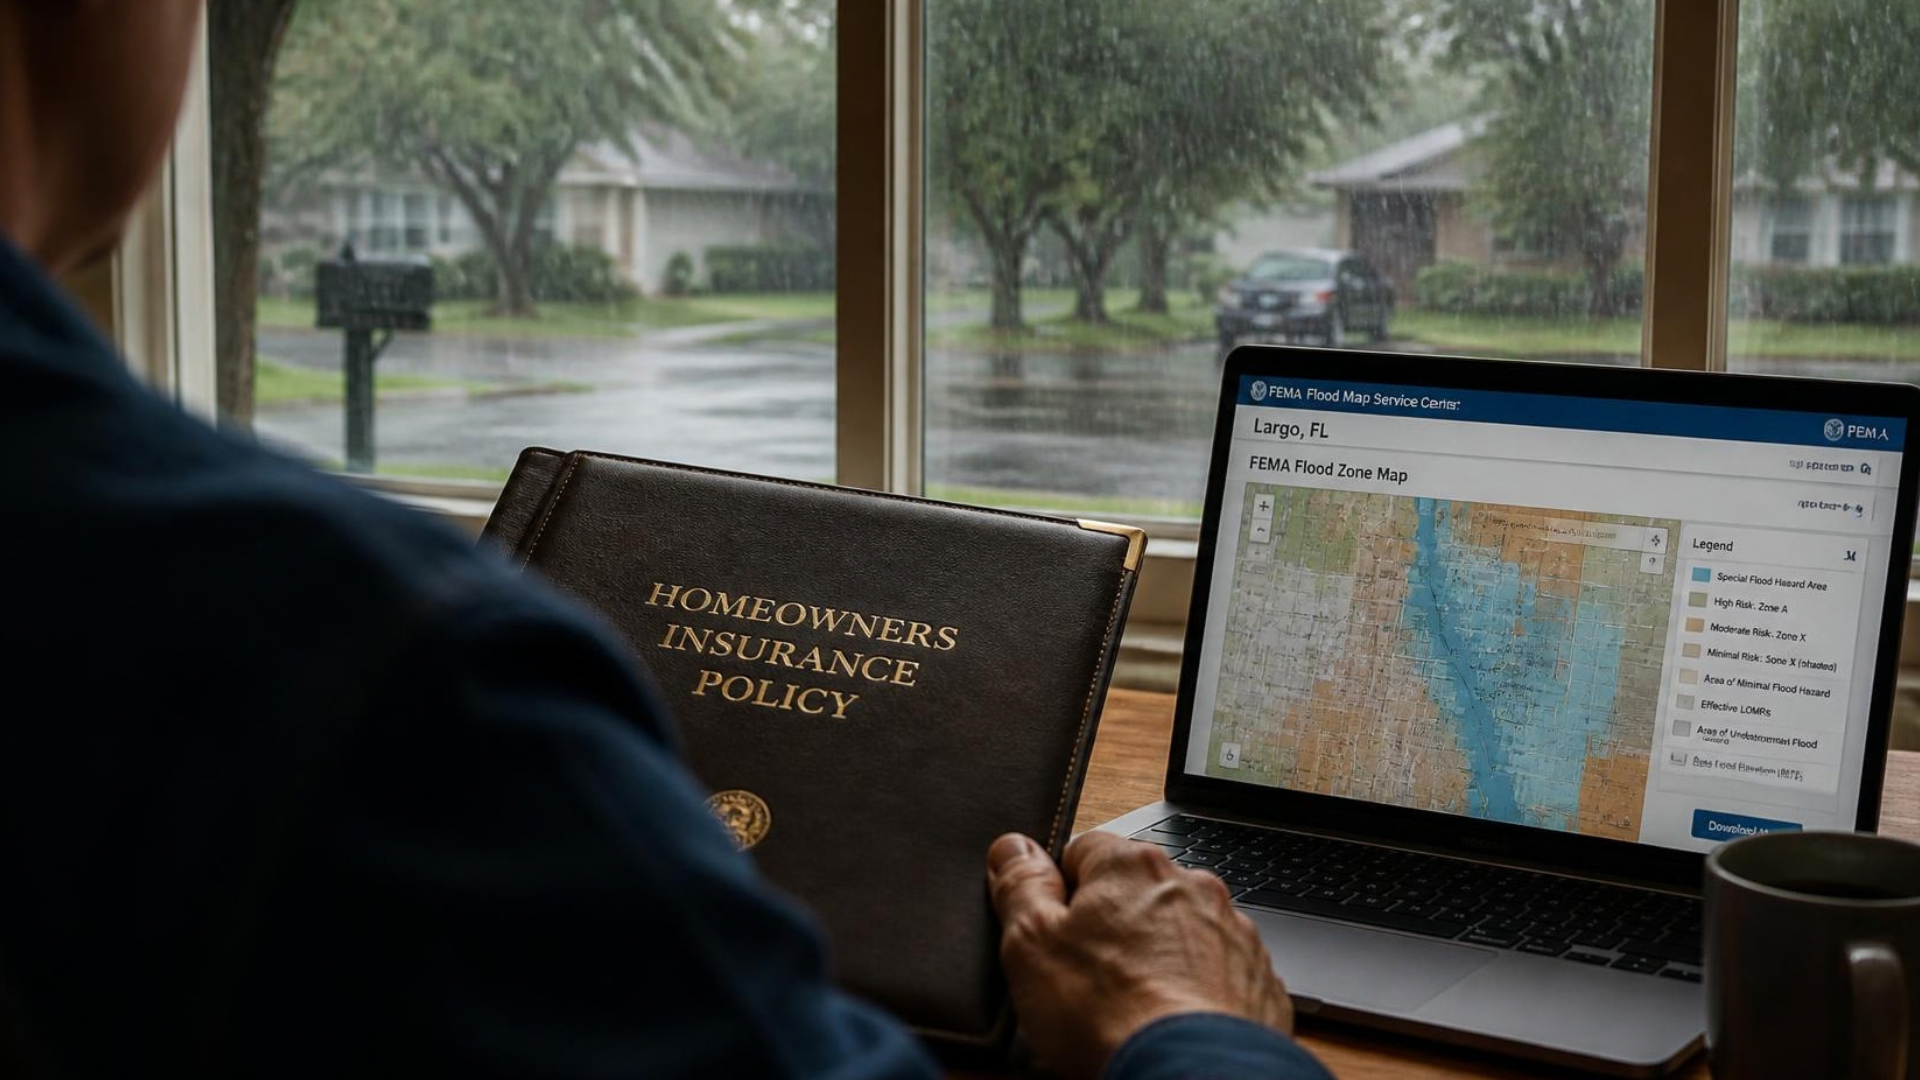
Flooding is another issue Largo homeowners should evaluate carefully. Standard homeowners insurance generally does not cover flooding caused by rising water or storm surge. Flood insurance is normally purchased separately.
Even homeowners who live away from the immediate coastline can experience flooding from heavy rainfall, overwhelmed drainage systems, or nearby waterways.
Individual flood risk depends on factors such as elevation, flood zone, drainage characteristics, and location. A homeowner should not assume that living several miles from the beach automatically eliminates flood exposure.
Ackerman Insurance can help homeowners consider flood insurance separately from their homeowners coverage.
Insurance for Largo Condominiums and Townhomes
Largo’s residential market includes more than traditional single-family homes. Condominium and townhome owners may have different insurance responsibilities depending on the ownership structure and association documents.
Condo owners typically need to understand the association’s master insurance policy before selecting individual unit-owner coverage. Townhome insurance requirements can also vary.
A careful review can help clarify which building components, personal belongings, improvements, and liability exposures are the individual owner’s responsibility.
How to Find Affordable Homeowners Insurance in Largo
Finding competitive homeowners insurance requires balancing price, deductibles, limits, and available protection. A lower premium may not represent better value if the policy contains significantly higher deductibles or reduced coverage.
Potential ways to manage insurance costs include:
- Comparing available insurance carriers
- Reviewing dwelling replacement cost estimates
- Documenting wind mitigation improvements
- Maintaining or replacing aging roofing systems
- Updating older electrical and plumbing systems
- Selecting appropriate deductibles
- Reviewing available bundling discounts
- Reassessing coverage after renovations
An independent insurance agency can help homeowners evaluate available choices rather than relying solely on the first quote received.
Why Work With Ackerman Insurance?
At Ackerman Insurance, we believe homeowners deserve to understand their coverage before they need to file a claim.
Our team helps Largo homeowners evaluate insurance options based on their property characteristics, coverage requirements, financial priorities, and available carriers.
We can assist with reviewing dwelling protection, personal property limits, liability coverage, hurricane deductibles, wind mitigation opportunities, and flood insurance considerations.
Whether you’re purchasing an established Largo home, relocating to Pinellas County, or evaluating your current insurance costs, Ackerman Insurance can help you make a more informed decision.
Serving Largo From Our Tampa Bay Office
Ackerman Insurance
401 East Jackson Street, Suite 2340
Tampa, FL 33602
Phone: (813) 365-3233
Our Tampa office serves homeowners throughout the greater Tampa Bay area, including Largo and surrounding Pinellas County communities.
Request a Homeowners Insurance Quote in Largo, Florida
Your home deserves protection that reflects its actual value, condition, and exposure to potential losses.
If you’re comparing homeowners insurance in Largo, FL, let Ackerman Insurance help you explore available coverage options.
Contact Ackerman Insurance today at (813) 365-3233 to request a homeowners insurance quote for your Largo property.
Frequently Asked Questions About Largo Homeowners Insurance
What affects homeowners insurance rates in Largo, Florida?
Insurance premiums can be influenced by the home’s age, roof condition, replacement cost, construction, location, claims history, coverage limits, deductibles, and wind mitigation features.
Do older homes in Largo require special insurance inspections?
Some insurers request four-point inspections for older properties. These inspections generally review roofing, electrical, plumbing, and HVAC systems to help determine insurance eligibility.
Does homeowners insurance cover hurricane damage in Largo?
Homeowners insurance may cover qualifying hurricane-related wind damage, subject to the policy’s terms, exclusions, coverage limits, and hurricane deductible. Flooding from storm surge generally requires separate flood coverage.
Is flood insurance necessary if my Largo home isn’t near the beach?
Flood insurance may still be worth considering because heavy rainfall, drainage problems, and inland waterways can create flood exposure. Risk should be evaluated for the individual property.
Can a new roof reduce my homeowners insurance premium?
A newer roof may improve insurance eligibility or pricing, depending on its materials, installation, wind mitigation characteristics, and the insurance carrier.
Can Ackerman Insurance help compare multiple homeowners insurance companies?
Ackerman Insurance can help homeowners review options from available carriers and compare important policy differences, including premiums, coverage limits, and deductibles.
Should I review my homeowners insurance after renovating my Largo home?
Yes. Significant renovations can change rebuilding costs and coverage requirements. Homeowners should report major improvements and review their dwelling and other relevant coverage limits.
Recent Comments